Condo Market SF › Market reports
The Marlow at Clay and Van Ness: two closings this year at $1,442 a foot, both inside two weeks and both above the building's 2017 high
Every 2026 closing at The Marlow, the 2014 building on Clay at Van Ness where Nob Hill meets Pacific Heights, against the record since 2014
Two closings at 1788 Clay Street through October 15, against two in the 2025 window; $2.8 million of volume against $1.9 million. Median sale $1,410,000; median $1,442 a square foot, against $1,070 last year and $1,334 in 2017, the building's high in a year with five or more closings. #809, bought in November 2021 for $1,642,000, sold for $1,810,000 after 13 days; #811, bought new in February 2014 for $828,000, sold for $1,010,000 after 14.
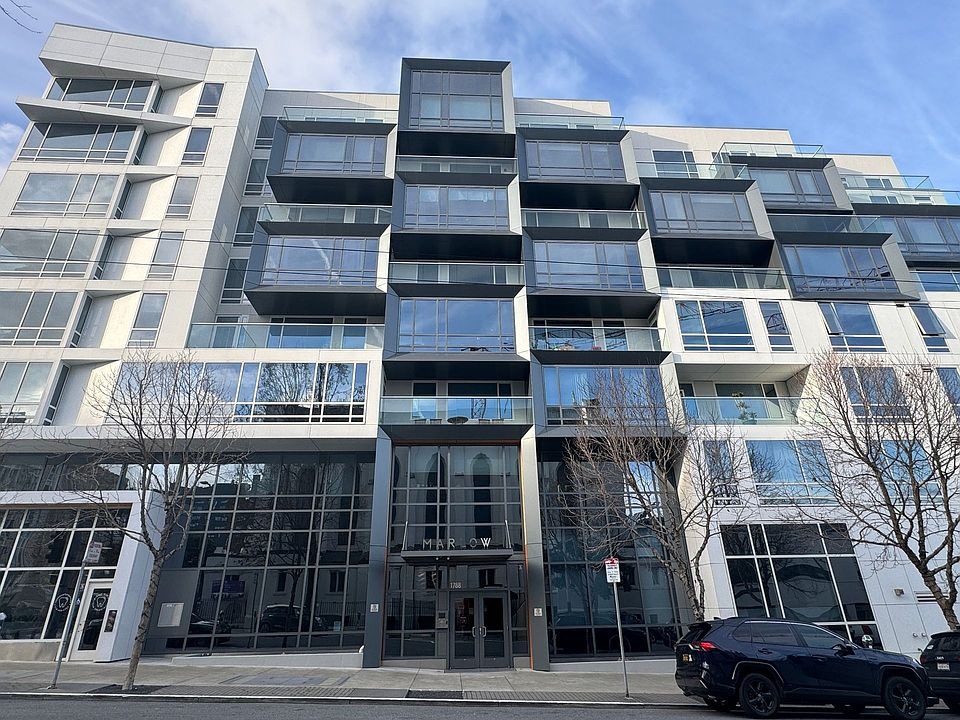
The Marlow's two sales this year both cleared the building's old high and both went inside two weeks. Two condominiums closed at 1788 Clay Street between January 1 and October 15, 2026, against two in the same window of 2025; $2,820,000 of volume against $1,869,000. The median sale is $1,410,000 and the median price per square foot is $1,442, against $1,070 last year and $1,334 in 2017, the building's high in any year with five or more closings; on two sales the figure is the midpoint of two units that landed within six dollars a foot of each other.
#809, a 1,253-square-foot two-bedroom, closed at $1,810,000 on June 3 after 13 days, $1,445 a foot; it was bought in November 2021 for $1,642,000, up 10.2 percent. #811, a 702-square-foot one-bedroom, closed at $1,010,000 on June 30 after 14 days, $1,439 a foot; it was bought new in February 2014 for $828,000, up 22 percent in twelve years. Both went inside two weeks.
The building dates from 2014, eight stories and 94 residences over 4,900 square feet of ground-floor retail, with a staffed desk and a courtyard with bocce and grills; dues on a 746-square-foot one-bedroom run $907 a month, and #511, 1,143 square feet, went from $1,235,000 new in March 2014 to a $1,480,000 contract in December 2018 (IMEG; RubyHome listing, #205; SocketSite).
2026 so far, against the same window in 2025
Closings at The Marlow between January 1 and October 15, 2026, set against January 1 to October 15, 2025. Days on market is median days from listing to contract on MLS-listed sales; "under 15 days" counts how many of those went into contract inside two weeks.
| Measure | 2025 (same window) | 2026 year to date |
|---|---|---|
| Closings | 2 | 2 |
| Dollar volume | $1,869,000 | $2,820,000 |
| Median sale price | $934,500 | $1,410,000 |
| Median $/sq ft | $1,070 | $1,442 |
| Median days on market | 62 | 14 |
| Under 15 days (of MLS sales) | 0 of 2 | 2 of 2 |
Year by year
Every recorded closing at The Marlow since February 2014, by calendar year. 2026 runs through October 15, 2026. Days on market is available for MLS-listed sales from 2020 onward.
| Year | Closings | Median price | Median $/sq ft | Median days | High sale |
|---|---|---|---|---|---|
| 2016 | 2 | $1,314,000 | $1,319 | — | $1,716,000 |
| 2017 | 8 | $1,370,000 | $1,334 | — | $1,680,000 |
| 2018 | 2 | $1,462,000 | $1,287 | — | $1,480,000 |
| 2019 | 5 | $985,000 | $1,276 | — | $1,415,000 |
| 2020 | 4 | $967,500 | $1,228 | 28 | $1,530,000 |
| 2021 | 6 | $1,142,500 | $1,287 | 24 | $1,642,000 |
| 2022 | 2 | $1,222,500 | $1,401 | 10 | $1,400,000 |
| 2023 | 1 | $850,000 | $1,267 | — | $850,000 |
| 2024 | 5 | $845,000 | $1,122 | 70 | $1,450,000 |
| 2025 | 3 | $1,149,000 | $1,178 | 36 | $1,270,000 |
| 2026 | 2 | $1,410,000 | $1,442 | 14 | $1,810,000 |
The building's highest median price per square foot in any year with five or more closings was $1,334 in 2017 (8 closings). 2026 year to date stands at $1,442.
By bedroom count, 2025 against 2026
| Beds | 2025 closings | 2025 median | 2025 $/sq ft | 2026 closings | 2026 median | 2026 $/sq ft |
|---|---|---|---|---|---|---|
| 1 bed | 1 | $720,000 | $963 | 1 | $1,010,000 | $1,439 |
| 2 bed | 2 | $1,209,500 | $1,272 | 1 | $1,810,000 | $1,445 |
Every closing in 2026
All 2 closings through October 15, 2026, highest price first. Square footage and days on market are as recorded on the MLS; county-recorded transfers that never listed show no days.
| Unit | Bd | Sq ft | Sold | $/sq ft | Days | Closed |
|---|---|---|---|---|---|---|
| 1788 Clay Street, #809 | 2 | 1,253 | $1,810,000 | $1,445 | 13 | Jun 03 |
| 1788 Clay Street, #811 | 1 | 702 | $1,010,000 | $1,439 | 14 | Jun 30 |
Paired resales
Units that closed in 2026 and had a prior recorded sale in the same building. The change is gross, before any improvements, fees or carrying costs.
| Unit | Prior sale | Prior price | 2026 sale | 2026 price | Change |
|---|---|---|---|---|---|
| 1788 Clay Street, #809 | Nov 2021 | $1,642,000 | Jun 2026 | $1,810,000 | +10.2% |
| 1788 Clay Street, #811 | Feb 2014 | $828,000 | Jun 2026 | $1,010,000 | +22.0% |
2 of these resold above the prior price, 0 below.
Clay at Van Ness
The building holds the corner of Clay and Van Ness, with a second address at 1800 Van Ness, two blocks from the Polk Street corridor (IMEG; Elliman listing, #801). Polk's storefronts turned over in 2025 and 2026: Lord Stanley at 2065 Polk and Broadway closed in March 2025, with the Jupiter Room under construction in its place for a fall 2026 opening; the Peet's at 2193 Polk closed and Bageletto was announced for the space in April 2026; MIXT opened at Polk and Green (SF Standard; Warrin). Van Ness got its bus rapid transit lanes in April 2022, and in April 2025 the Board of Supervisors lifted the formula-retail ban on the avenue (SFist; SFist).
No AI office of any size is within walking distance; the office figures in the paragraphs below describe SoMa, two miles east.
The timetable that every South of Market building now sits inside is the public-offering calendar. Anthropic filed a confidential draft registration with the SEC on June 1, 2026, a week after a funding round that set its valuation at $965 billion (TechCrunch). As of this week the Standard reports the Anthropic listing has been pushed to November, after the midterms, that OpenAI's has moved to 2027, and that Anthropic is weighing a lockup longer than the usual six months (SF Standard). The same piece carries a Redfin estimate that current and former OpenAI and Anthropic employees could in theory buy close to a third of the metro area's homes with their proceeds, and the counter-argument from UC Berkeley's Enrico Moretti and the Bay Area Council's Jeff Bellisario that the money is concentrated in fewer hands than past booms and that these firms create fewer jobs per dollar because so much goes to data centers rather than headcount. The record in this report ends on October 15. None of it reflects a single share that has been sold.
Two citywide facts frame every building figure here. First, the office recovery is lopsided: CBRE put Q3 2026 vacancy at 27.7 percent citywide, down 6.6 points in a year, but Avison Young splits that into roughly 12 percent for Class A and north of 31 percent for Class B, and a Presidio Bay executive told Bisnow the headline number is misleading for that reason (Bisnow). Second, the condo market is still digging out: the Chronicle's May analysis found that only eight Bay Area ZIP codes showed inflation-adjusted condo gains over the year, all of them in San Francisco, and that Noe Valley's typical condo remained close to $400,000 below its 2019 level in real terms (SF Chronicle).
How this was counted
Two records feed this review. The MLS layer is one row per listing and carries days on market and square footage. The county layer reaches back further and catches transfers that never listed, but records the same closing once per data source, so the two were merged on unit, date and price and each closing kept once. Below-market-rate units and transfers under $300,000 are listed but excluded from every median. "Same window" means January 1 to October 15 of each year. Nothing here is a valuation of any unit, and nothing here is advice.
Tim McMullen · CA DRE #02016832
[email protected] · (415) 691-9272
- https://therealdeal.com/san-francisco/2026/04/07/anthropic-signs-another-san-francisco-office-lease/
- https://therealdeal.com/san-francisco/2026/03/16/openai-inks-another-mission-bay-lease/
- https://sfstandard.com/2026/04/07/i-leaderboard-san-francisco-office/
- https://www.sfexaminer.com/news/the-city/sfs-high-office-vacancy-rate-drops-again-as-ai-fueled-recovery-shows-legs/article_14d60cc1-a6dc-4228-9a44-b5b8c4d36b8c.html
- https://techcrunch.com/2026/06/01/anthropic-files-to-go-public/
- https://sfstandard.com/pacific-standard-time/2026/10/14/pst-anthropic-openai-ipos-sf-wealth/
- https://www.bisnow.com/news/san-francisco/office/ai-surge-driving-sf-office-market-leasing-to-strong-totals-in-decades
- https://finance.yahoo.com/markets/stocks/articles/bay-area-condo-values-still-120000717.html
- https://imegcorp.com/?p=4296
- https://www.rubyhome.com/idx/1788-clay-street-san-francisco-ca-94109/1807257254_spid/
- https://socketsite.com/archives/tag/marlow
- https://www.elliman.com/listing/1788-clay-st-801-san-francisco-ca-94109/15591333
- https://sfstandard.com/2025/12/28/san-francisco-restaurant-bar-closures-2025/
- https://warrin.com/blog/polk-streets-new-storefronts-are-fixing-old-complaints-not-chasing-trends
- https://sfist.com/van-ness/
- https://sfist.com/2025/04/22/supervisors-lift-the-formula-retail-ban-on-van-ness-and-add-the-fillmore-safeway-property-to-that-exemption-too/
- The Marlow · 1788 Clay St · Nob Hill
Tim McMullen, CA DRE #02016832. Real estate services provided by Tim McMullen, Broker, CA DRE #02016832. Figures are from recorded sales; nothing here is an opinion of the value of any home.